
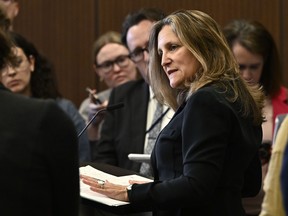
Freeland Optimistic on Canada’s Economy as Inflation Retreats
Canada’s finance minister, Chrystia Freeland, expressed a cautiously optimistic outlook for the country’s economy, noting a retreat in inflation and anticipated downward trends in interest rates, while acknowledging the absence of an impending recession. However, this positive assessment is tempered by significant political challenges for Prime Minister Justin Trudeau’s administration, driven by public frustration over the rising cost of living, housing shortages, and escalating crime rates. The political landscape is further complicated by speculation surrounding the potential involvement of Mark Carney, the former governor of the Bank of Canada and Bank of England, in the government’s financial strategy.
Freeland’s assessment is rooted in a realistic understanding of the numerous economic headwinds the country has faced, including the considerable disruptions caused by the COVID-19 pandemic, widespread inflation, and ongoing shortages. She underscored the demanding nature of the situation, acknowledging it as a “real trauma,” referencing the combined impact of the pandemic lockdowns, widespread mortality, and subsequent inflationary pressures. The current interest rate environment, with its impact on consumer credit card bills and mortgage costs, also received particular attention, highlighting the direct impact on individual citizens’ financial wellbeing. Freeland’s candid reflection – acknowledging that citizens are justified in holding the government accountable for managing these difficult circumstances – reveals a recognition of the strain on public confidence.
The situation is significantly influenced by intense political pressure, stemming from persistently low approval ratings for Trudeau’s Liberal Party. Current polls demonstrate a substantial deficit relative to the Conservative Party, suggesting a potential victory for Pierre Poilievre’s party in the upcoming election. Voter concerns regarding economic matters are paramount, with the current focus firmly on growth strategies and managing the nation’s finances. Poll data indicate that voters prioritize economic issues, specifically concerning growth support, and point to Chrystia Freeland’s handling of these matters as lacking the necessary emphasis on dynamism and resilience. The public perception of Freeland’s communication around these issues – an area under considerable scrutiny – appears to be a significant factor in the political stakes.
Rumours have circulated regarding discussions between Freeland and Mark Carney, a prominent figure with international experience in finance. Carney’s return to Canada after serving as governor of the Bank of England has led to speculation about his potential involvement in shaping Canada’s economic policy. While Carney offered veiled criticism regarding Freeland’s budget, which included a capital gains tax inclusion rate hike and a focus on intergenerational fairness, he also acknowledged the need for both solidarity and dynamism within the Canadian economy. This exchange highlights the complex and nuanced considerations surrounding economic leadership, especially given the current context of external pressures and domestic challenges. Furthermore, Freeland’s prior connection to Carney – his role as her son’s godfather – adds another layer to the dynamic, suggesting a long-standing relationship that could influence the strategic direction of the government’s financial policies.
Freeland has actively sought to counter these concerns through a series of meetings with business leaders in New York and Washington, emphasizing the government’s commitment to setting a fiscally responsible tone. She highlighted international investors’ enthusiasm for Canadian debt, noting that foreign holdings reached a record $54 billion over the past six months. This demonstrates a positive reception to Canada’s economic positioning, particularly in comparison to other Group of Seven nations, where deficits are considerably higher. Freeland’s data-driven approach – demonstrating that Canada’s fiscal circumstances are more favorable than those of the United States – reflects a strategy designed to underscore confidence in the government’s ability to manage the nation’s finances. Despite anticipated deficits of 1.3 percent of GDP next year, a level matched only by Germany, Freeland maintains a commitment to reducing deficits to less than 1 percent of GDP by 2026-27, a strategy aimed at achieving long-term fiscal sustainability.
However, Freeland’s efforts have faced scrutiny, particularly concerning the increased government spending, which currently represents 8 percent of GDP – the highest level since the early 1990s, outside the COVID-19 crisis. The government’s approach to addressing these challenges – including the capital gains tax inclusion rate hike – has generated considerable debate, particularly within the business community. While Freeland and Carney have a history of collaboration, characterized by open communication, their differing perspectives on the budget – with Carney emphasizing the need for ‘dynamism’ alongside ‘fairness’ – underscores the complexities inherent in navigating economic crises and shaping national economic strategy. The ongoing uncertainty surrounding Freeland’s position within the government remains a key factor, underscored by Trudeau’s conversations with Carney and the prime minister’s stated confidence in Freeland’s continued role.
