
Canadians’ Mortgage Borrowing Surge to Record High Since 2007
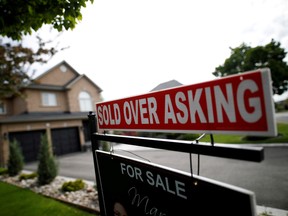
Canadians are increasingly taking on mortgage debt at a pace more than double the historical average, reflecting a significant shift in the housing market following a period of pandemic-driven booms. Statistics Canada reported on Thursday that the total value of residential mortgages rose by 1.2 percent in June, reaching $1.73 trillion (approximately $1.4 trillion). This represents the fastest monthly increase in real estate-secured loans since 2007, indicating a sustained level of demand within the Canadian housing sector. The trend has prompted analysts to examine the underlying factors contributing to this heightened borrowing activity.
Understanding the Surge in Mortgage Demand
The rapid escalation in mortgage uptake is fundamentally tied to several key developments observed during and following the COVID-19 pandemic. Primarily, Canadians sought more living space, a desire fueled by shifting priorities related to work, family, and lifestyle. The pandemic triggered a surge in housing sales and prices, reaching record highs. This, in turn, drove increased demand for mortgages to finance property purchases. The shift wasn’t simply a reaction to pandemic conditions; it represented a broader reevaluation of housing needs and preferences within the Canadian population. Furthermore, lower interest rates, maintained for an extended period, contributed significantly to the affordability of mortgages, emboldening prospective homebuyers to take on larger financial commitments.
The Financial Context: Rising Debt and Historical Comparisons
Beyond the immediate demand, the financial context surrounding mortgage lending has played a crucial role. Over the past year, the total amount of real estate-related debt outstanding in Canada has increased by 9.2 percent, marking the largest such rise since 2008. This substantial growth underscores the evolving dynamics of the Canadian mortgage market. It’s important to note that the rise in mortgage debt isn’t occurring in a vacuum. Statistics Canada highlighted a time lag between the sale of a home and the actual receipt of mortgage funds. This lag suggests that the increase in outstanding debt is not necessarily a reflection of immediate purchasing activity, but rather a gradual accumulation of financing as sales transactions move through the closing process. Comparisons to historical lending patterns are particularly noteworthy, as the current pace of mortgage issuance far surpasses previous levels, signaling a distinct departure from the more moderate borrowing trends of the years preceding the pandemic.
Market Dynamics and the Cooling Housing Sector
As mortgage debt continues to increase, experts anticipate a slowing in Canada’s housing market. Sales volumes have fallen for the past four months, indicating a moderation in the pace of property transactions. This slowdown is likely to be a direct consequence of the rising debt levels. The link between mortgage lending and the broader housing market is a cyclical one: increased borrowing can fuel price appreciation, but as lending conditions tighten, it can also contribute to price corrections. Statistics Canada explicitly stated that “there is normally a time lag between the sale of a home and the actual receipt of mortgage funds.” This lag reveals a critical element: the influx of mortgage dollars is not immediately translating into a sustained increase in property sales, suggesting a potential adjustment in the market as lending standards may respond to the evolving debt landscape. The longer-term implications will hinge on how the market responds to both rising borrowing and falling sales.
External Commentary and Related Trends
Bloomberg.com reported that the Canadian housing market is tightening following a fourth consecutive monthly drop in sales. Several factors contribute to this trend. Residential sales are cooling amid rising interest rates in Canada, while condo demand is increasing in Canada’s major cities, primarily due to surging rental costs. Concerns have been raised that zero-down mortgages in Canada could mirror similar risks seen in the U.S. subprime mortgage market of 2008. In Ontario, the competitive bidding wars that have characterized the housing market have prompted one company to offer employees $20,000 towards down payments. These developments underscore the interconnectedness of the Canadian housing sector, highlighting both the opportunities and vulnerabilities presented by evolving mortgage practices and overall market conditions.
